preferred on

Points of Focus
- Nearly 99% of stablecoins are dollar-denominated, extending the dollar’s dominance into blockchain-based finance.
- The US is using regulated private stablecoins to expand digital dollar distribution rather than pursuing a retail CBDC.
- Dollar stablecoins could accelerate digital dollarization and weaken monetary-policy control in economies with vulnerable local currencies.
The digital currency race already has a clear frontrunner, and it isn’t a central bank digital currency (CBDC).
According to the International Monetary Fund, nearly 99% of stablecoins are denominated in US dollars, while the Bank for International Settlements puts the figure at about 98%. With the stablecoin market officially surpassing $300 billion, private issuers have built a global network for moving dollars across blockchains.
Meanwhile, central banks from Europe to China and India are developing, piloting or expanding CBDCs partly to keep sovereign money relevant in an increasingly digital economy.
That creates an awkward mismatch. Governments can make domestic currencies faster, programmable and digital, but they cannot make users prefer them. If businesses and individuals choose stablecoins because they want dollars, digitizing the local currency does not solve the underlying problem.
The emerging contest is therefore not simply stablecoins versus CBDCs, but whether digital finance will reinforce the dollar’s existing global dominance.
The dollar won crypto’s first currency race
There was nothing inevitable about stablecoins becoming almost entirely dollar-denominated. Blockchains can support tokens linked to euros, pounds, yen or virtually any other currency. Yet the market overwhelmingly settled around the dollar.
The explanation begins outside crypto.
The dollar was already deeply embedded in international trade, financial markets, and cross-border funding. Stablecoins rode the existing demand.
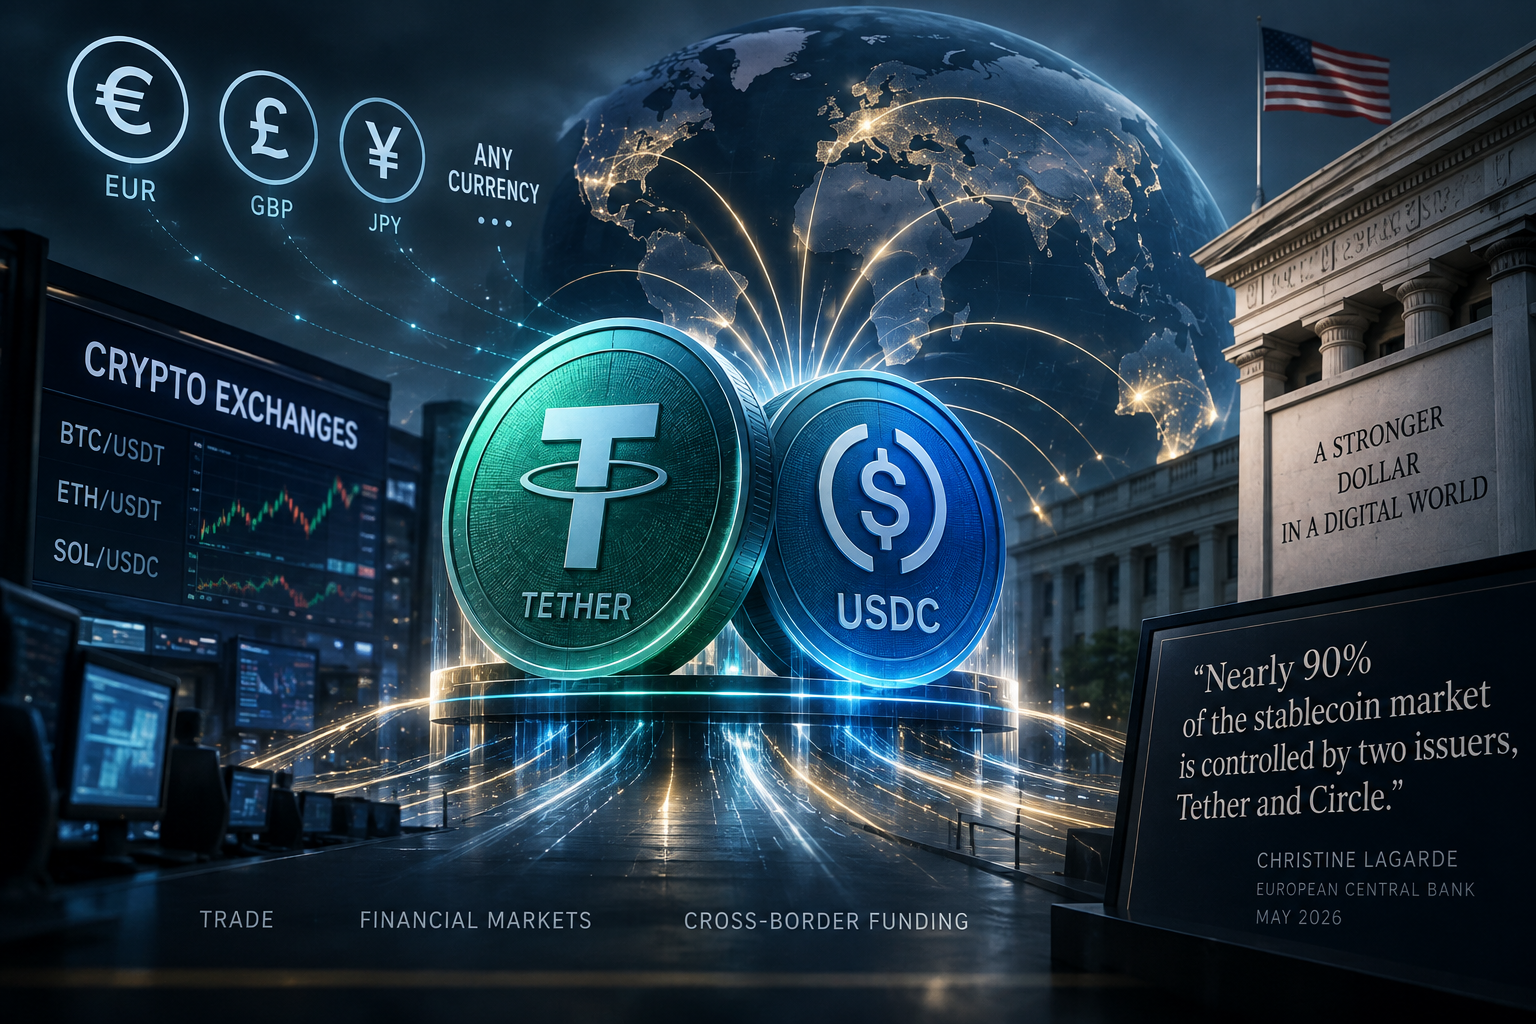
Crypto exchanges quoted assets against dollar stablecoins, market makers accumulated them, and traders used them to move capital between venues. The European Central Bank (ECB) President Christine Lagarde stated in May 2026 that nearly 90% of the stablecoin market was controlled by just two issuers, Tether and Circle.
Stablecoins have built a new distribution channel for the world’s dominant currency. And the US increasingly sees it as an advantage.
That concentration exists at two levels: dollar-denominated tokens dominate by currency, while Tether and Circle dominate issuance within that dollar-based market.
America is embracing the digital dollar it didn’t issue
The US has taken a different approach to digital money. Instead of launching a retail CBDC, Washington created a regulatory framework for private stablecoins through the GENIUS Act.
When the law was signed in July 2025, Treasury Secretary Scott Bessent said stablecoins could expand global access to dollars, strengthen the currency’s reserve role and increase demand for US Treasurys.
The model effectively outsources digital-dollar distribution. Private companies issue stablecoins, assets such as short-term Treasurys support their reserves, and blockchains distribute them globally. Unlike a conventional CBDC, the central bank does not need to build the distribution network itself.
For other central banks, the same trend looks very different
What Washington sees as an opportunity can look like a sovereignty problem elsewhere.
The European Central Bank (ECB) has warned that dollar stablecoins, which dominate the global market, could weaken the euro’s role if they become widely used for payments and tokenized finance.
The risk grows if households and businesses increasingly save and transact in digital dollars, reducing central banks’ influence over domestic financial conditions.
The BIS warns that dollar-stablecoin adoption could accelerate currency substitution in emerging economies, particularly where inflation, exchange-rate instability or weak confidence already discourage holding local currencies.
Otto Jacobsson, Chapter Lead, Digital Assets Association UK, stated in a conversation with AlphaWire,
“In many emerging markets, people are turning to dollar stablecoins because they want exposure to the dollar, particularly where high inflation and currency instability have eroded confidence in their domestic currency. The appeal is therefore about more than payments technology: stablecoins can provide a practical way to access a currency perceived as a safe haven.
“The challenge for non-dollar currencies is that there is still limited liquidity and adoption across their stablecoin markets. As regulation becomes clearer and more GBP stablecoins come to market, we should see that start to change. At the DAA UK, we expect greater availability of regulated GBP stablecoins to unlock use cases that are specific to the UK economy and support more meaningful sterling-denominated activity onchain.
“Dollar stablecoins are likely to remain dominant, but that does not mean dollarisation is inevitable. The growth of credible, liquid alternatives will be critical if central banks want their currencies to remain relevant in an increasingly digital financial system.”
A digital peso is still a peso
Suppose a country launches a CBDC with instant settlement, negligible fees, and widespread acceptance. However, it still may not impress someone buying USDT or USDC specifically for dollar exposure.
This separates the technology problem from the currency problem. In economies with persistent inflation or unstable exchange rates, dollar-linked stablecoins offer access to a different monetary unit, which a domestic CBDC cannot replicate. Argentina offers a clear example: years of high inflation and repeated peso depreciation have strengthened demand for dollar-denominated alternatives as a store of value.
Foreign-currency stablecoins could weaken monetary-policy transmission and encourage currency substitution in Europe.
Foreign-currency stablecoins could weaken monetary-policy transmission and encourage currency substitution in Europe. If households and businesses increasingly save, transact or settle payments in dollar-denominated stablecoins instead of euros, a growing share of financial activity could become less responsive to ECB interest-rate decisions.
Stablecoins also make dollar exposure easier to obtain without a US bank account, potentially encouraging users to substitute tokenized dollars for the euro in some financial activities.
This creates a paradox. Countries concerned about monetary sovereignty may have citizens with strong incentives to seek alternatives to their domestic currency.
CBDCs and stablecoins may not actually be fighting the same battle
Stablecoins and CBDCs are not necessarily competing for the same role.
CBDCs provide sovereign digital money and can reduce reliance on private payment infrastructure. Stablecoins instead offer private distribution, blockchain interoperability, and easy access to globally demanded currencies.
The distinction also puts stablecoin adoption in perspective. The BIS estimates stablecoins generated about $35 trillion in transaction volume in 2025, but only around $390 billion involved payment-related flows.
Stablecoins are therefore far from replacing conventional payment systems. Their significance may lie elsewhere. Stablecoins show how quickly an established currency can spread when it becomes easily transferable across blockchain networks.
Sovereignty may depend on networks, not just currencies
Europe’s response demonstrates how governments may defend monetary sovereignty.
The digital euro aims to preserve access to sovereign money, while the Eurosystem is developing infrastructure for settling distributed-ledger transactions in central bank money. Other countries are exploring cross-border CBDC links and connections between instant-payment systems.
Governments can also regulate foreign stablecoin issuers, encourage local-currency alternatives, and impose reserve, custody and redemption requirements. The goal is to make domestic currencies more competitive with dollar stablecoins.
But technology and regulation face a fundamental limitation. They can make currencies easier to use, but they cannot determine which currency people actually want to hold.
Digitizing money doesn’t erase the currency hierarchy
The 99% figure suggests digitization may reinforce the existing monetary order rather than disrupt it.
The dollar entered the blockchain era with decades-old advantages: deep capital markets, global liquidity, widespread trade use, and international demand. Stablecoins turned those advantages into digital network effects.
CBDCs can give competing currencies faster settlement, programmable infrastructure, and sovereign digital rails, but they cannot create international demand for the underlying currency.
This may define the next stage of digital money. The key question is not which central bank builds the best CBDC, but which currency people choose when moving between currencies becomes easier than ever.