preferred on

Points of Focus
- SIMD-0553 crossed Solana’s 15% validator signaling threshold on August 5, 2026.
- The proposal could push daily SOL burns from 648 to 9,000 coins.
- SIMD-0550 needed about 3 million more SOL in signaling support by August 18.
Solana’s transaction fee has stayed nearly flat since the network launched: a fixed 5,000 lamports per signature, regardless of how much computing power the transaction actually consumes.
A proposal now moving through formal validator voting would end that, and the numbers behind it are large enough to matter well beyond the protocol-engineering crowd that usually tracks Solana Improvement Documents.
What SIMD-0553 actually changes
SIMD-0553, authored by a researcher known as Cavey at the Temporal research team, splits Solana’s flat base fee into two pieces. Every transaction would still pay a 2,500-lamport inclusion fee to the validator who includes it. A separate resource fee, calculated from the compute units the transaction actually requests, would be burned in full rather than paid to anyone.
The mechanical shift matters because Solana’s current fee structure charges roughly the same amount whether a transaction uses a fraction of its requested compute budget or all of it. The network’s own transaction scheduler packs blocks against requested compute, not actual usage, so over-reservation currently holds block space that other transactions could otherwise fill. A transaction that reserves far more compute than it uses pays the same base fee as one that uses exactly what it requested, which means the current model has no built-in penalty for wasteful reservation.
SIMD-0553 prices that resource on its own terms and destroys the proceeds instead of routing them to validators as revenue. The design choice to burn rather than redistribute is deliberate: routing the resource fee to validators would have made the proposal fee-neutral for the network’s overall economics, moving money from users to block producers without changing token supply.
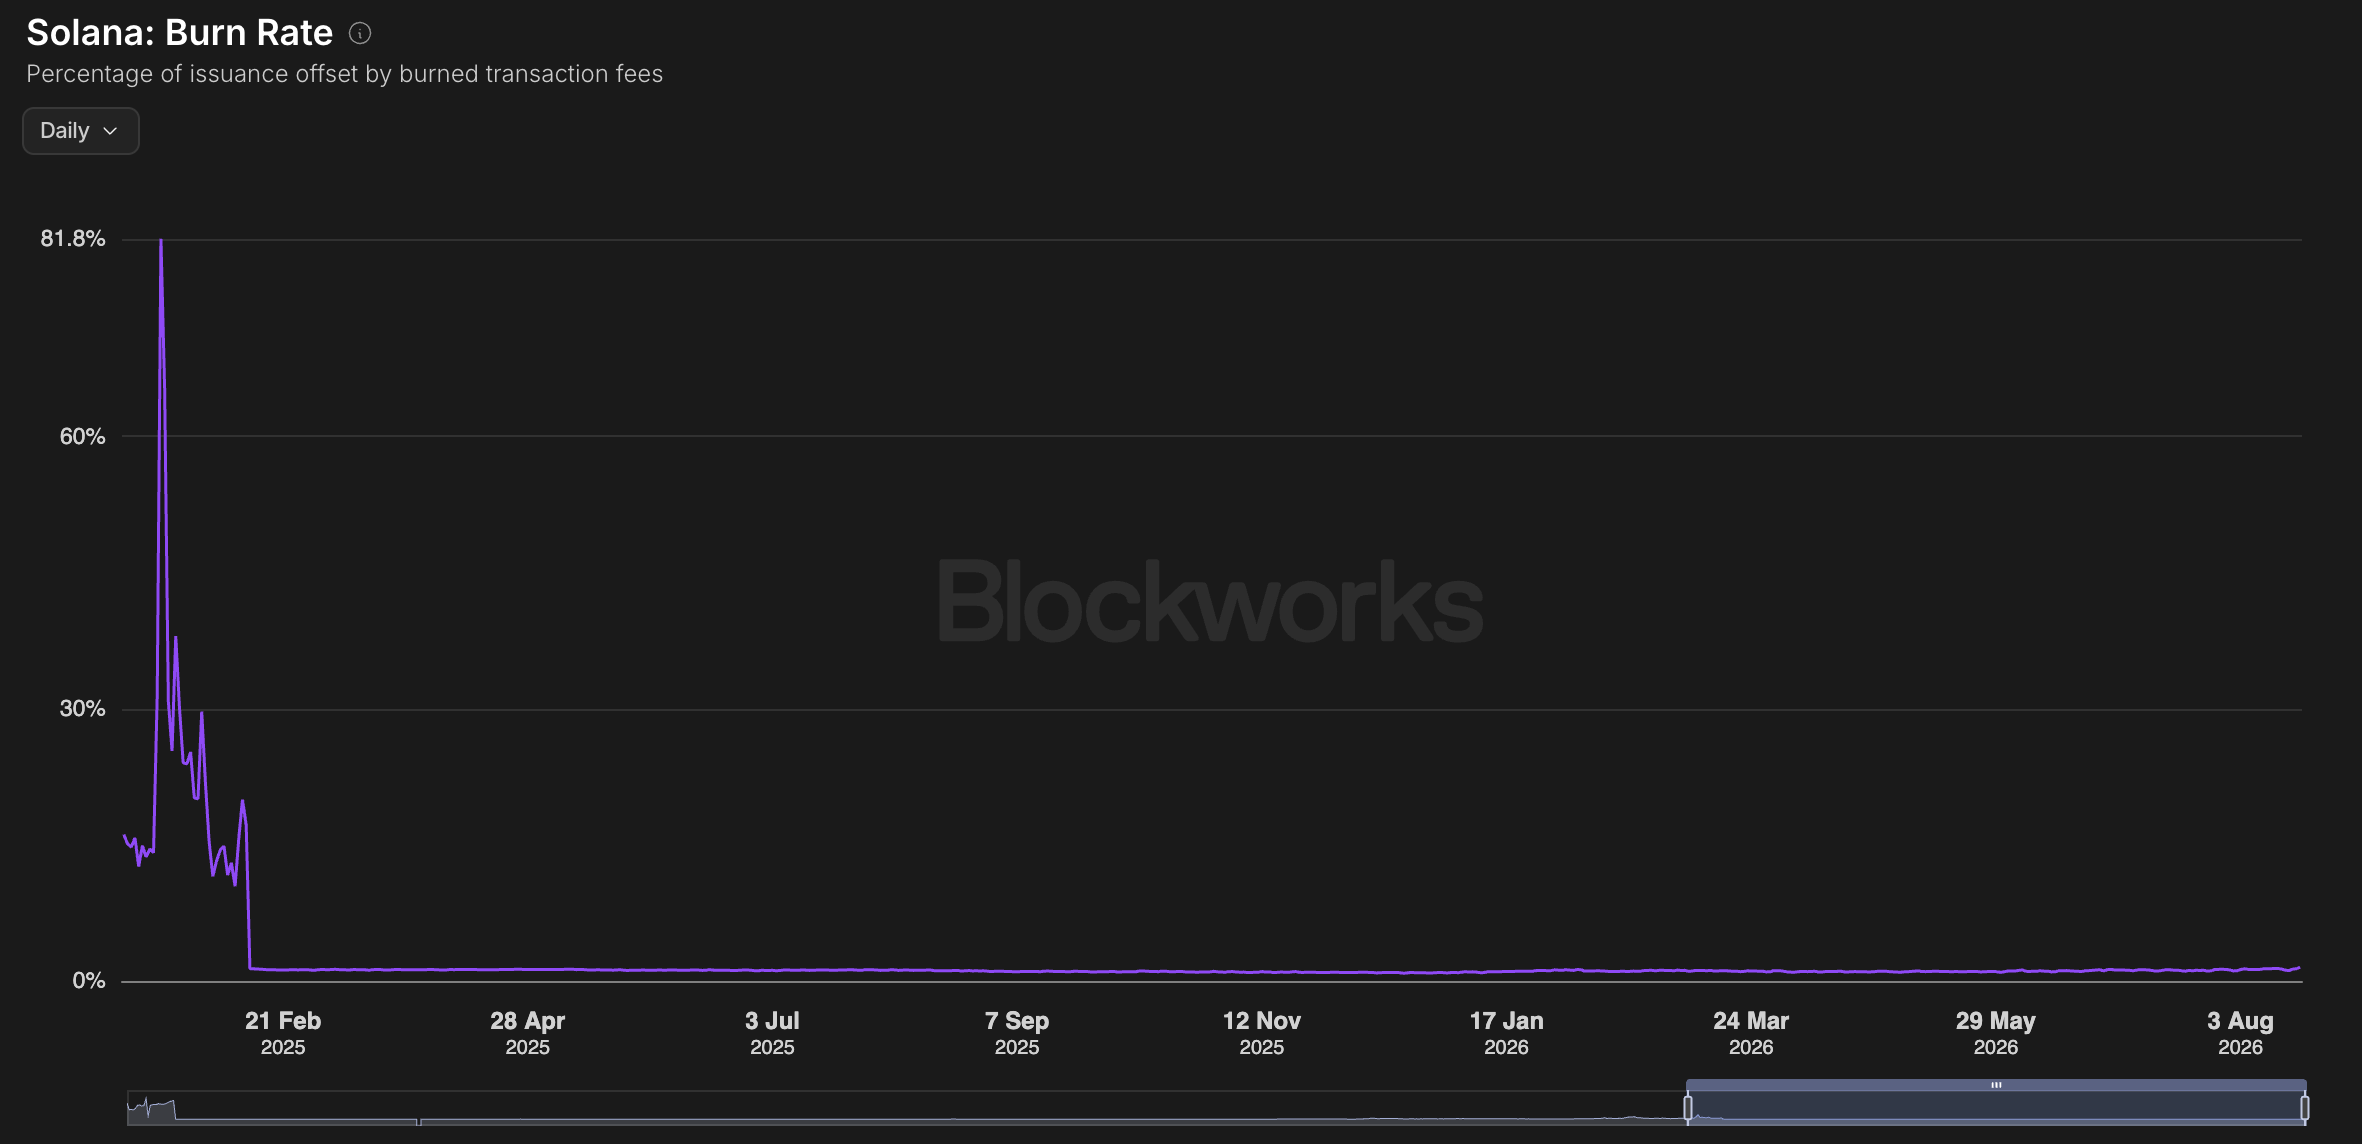
Burning it instead ties transaction activity to token scarcity, which is the same mechanism a stock buyback uses to link corporate cash flow to per-share value.
The number that turns a technical proposal into a real story
Anza, Solana’s core protocol development firm, modeled SIMD-0553’s effect using May 2026 network activity and estimated it would lift daily SOL burns from around 648 SOL, worth roughly $47,000 at current prices, to as much as 9,000 SOL, or about $650,000 a day. Annualized, that amounts to approximately 3.3 million SOL removed from the circulating supply each year.
they'll all get done this year.
123 already passed & almost code complete.
547 (discussion) & 553 (SIMD) are the same thing.
553 and 550 are both a concept ACK for Anza.— Brennan Watt (@bw_solana) June 20, 2026
Cross-checking that estimate against SOL’s price of $72 in August 2026 confirms it holds together: 9,000 SOL at $72 comes to about $648,000, consistent with the $650,000 figure Anza published. That consistency matters because it means the burn estimate is not an inflated headline number detached from current market pricing.
The scale becomes clearer set against Solana’s existing fee revenue. From Aug 2-7, the network collected between 6,400 and 9,600 SOL per day in combined base fees, priority fees, and Jito tips. Base fees, the specific revenue stream SIMD-0553 targets, were already the smallest of the three.
A proposal that could burn up to 9,000 SOL a day is being layered onto a network whose current daily take across all fee categories is roughly in that same range, which is why this proposal reads as aggressive rather than incremental.
SIMD-0550 attacks the same problem from the supply side
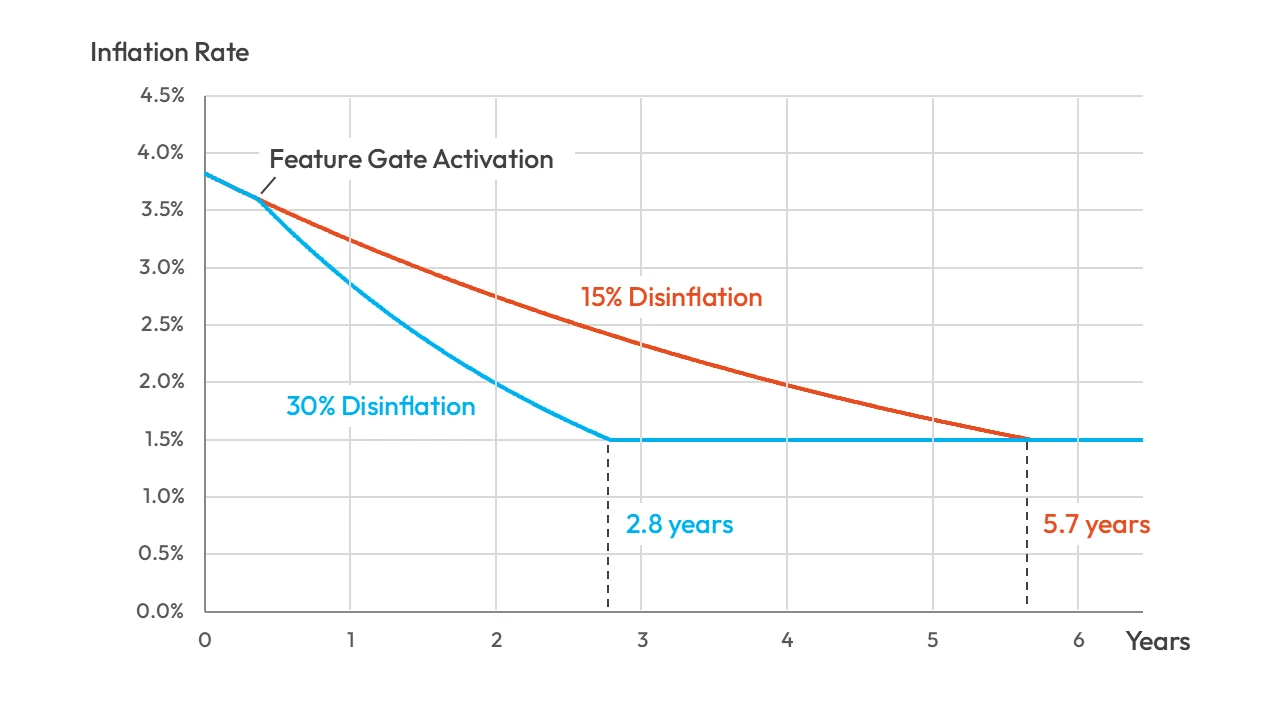
SIMD-0553 does not travel alone. It is paired with SIMD-0550, a proposal that doubles Solana’s annual disinflation rate from 15% to 30%, moving the network’s terminal 1.5% inflation floor from a projected 2032 arrival to 2029. Thus putting the six-year impact at roughly 18.9 million SOL in avoided future emissions, worth about $1.36 billion at current prices.
Averaging that six-year total works out to roughly 3.15 million SOL in avoided annual emissions, a figure no source reviewed for this piece states outright but one useful for comparing SIMD-0550’s yearly impact against SIMD-0553’s roughly 3.3 million SOL in annual burns.
The two proposals are of similar order of magnitude, and Temporal’s analysis of their combined effect estimates that net annual SOL supply growth would fall to approximately 1.05% by 2029, undershooting Solana’s stated 1.5% terminal target.
Together, the two proposals are grouped under a governance package labeled SGP-0003.
Who actually gains and who loses
A fee change that burns revenue instead of paying it to validators is not neutral for the people who run the network. Under the current model, priority fees and Jito tips already flow entirely to validators, a split that became fully validator-favorable after a separate proposal, SIMD-0096, passed in early July 2026.
SIMD-0553 does not touch that priority-fee split. It targets only the base fee, and the resource portion of that base fee would be destroyed rather than distributed, directly reducing validator revenue relative to the current flat-fee model.
Token holders and delegators sit on the other side of that trade. Tighter net supply growth benefits anyone holding SOL without running a validator, as it reduces dilution over time. Solana’s governance system includes a mechanism called staker sovereignty, which allows delegators to override their validator’s vote using their stake weight. That detail matters here specifically, since it means a validator facing reduced fee revenue and a delegator benefiting from tighter supply are not guaranteed to vote the same way, even when the delegator’s stake sits behind that exact validator.
4/ Stakers sovereignty
Delegated your stake but disagree with how your validator voted? Or has your validator not voted at all?
Delegators can now override the validator based on the delegator’s stake weight at https://t.co/0z7aWDWWu3
— Solana Foundation (@SolanaFndn) July 1, 2026
In practice, this creates three distinct constituencies rather than a simple two-sided fight. Large validators running at scale, where fee revenue is a meaningful share of operating income, have a direct incentive to resist a change that burns part of their revenue base.
Smaller validators, many of whom already operate closer to breakeven, may weigh the long-term health of a scarcer, more valuable token more heavily than a marginal revenue cut. And delegators who can override their validator’s vote entirely sit outside both calculations, weighing only the supply-side benefit to their own holdings.
DeFi Development Corp, a publicly traded company that holds SOL as a treasury asset, published a statement on August 4, backing both proposals and framing them as “meaningful steps toward a stronger and more sustainable economic model.”
That endorsement came from a corporate holder with no validator infrastructure to protect and a direct financial interest in tighter token supply, which is exactly the kind of stakeholder SIMD-0553’s design favors.
The case for skepticism
Anza’s burn estimates are modeled on May 2026 network activity. If on-chain transaction volume softens in the second half of 2026, the actual burn rate could land closer to 1,500 SOL a day in an initial phase rather than the headline 9,000 SOL figure, pushing the larger annualized number out indefinitely.
A proposal sized to a specific month’s activity is only as reliable as that month’s representative Solana’s transaction volume has swung meaningfully across 2026 already, including the record 1.01 billion non-vote transactions the network processed in the week ending August 2, a level of activity that may not repeat every month for the rest of the year.
That single data point cuts both ways for this piece’s argument. A record-setting week before the vote makes Anza’s May 2026 baseline look conservative rather than inflated, but one strong week is not the same as a sustained activity floor, and the proposal’s entire financial case rests on activity holding near recent highs rather than reverting toward the network’s own longer-run average.
There is also a governance mechanics risk distinct from the economic one. Both proposals need to clear their signaling threshold before a formal stake-weighted vote can even open, and missing that deadline does not kill a proposal outright but forces resubmission, a real delay even if the underlying economic case remains intact.
Where the vote stands right now
SIMD-0553 crossed the required 15% validator stake-weighted signaling threshold on August 5, 2026, with Helius’s validator stake providing the support that pushed it over the line, triggering an 11-epoch formal voting window.
SIMD-0550 had not yet cleared the same threshold as of early August, sitting an estimated one percentage point and roughly 3 million SOL short of the roughly 65.16 million SOL needed, against an Aug. 18 signaling deadline.
That gap matters on its own. If SIMD-0553 advances to a formal vote while SIMD-0550 misses its signaling window, Solana ends up burning fees more aggressively without also slowing new issuance, a partial version of the tokenomics overhaul rather than the full package Temporal modeled together.
What actually settles this
The test is specific and dated. SIMD-0553’s formal stake-weighted vote runs through its 11-epoch window opened on August 5, and SIMD-0550 either crosses its signaling threshold before August 18, or it does not.
A pass on both would mark the broadest rework of Solana’s base-layer economics attempted in the network’s history, layered onto a token that has traded in ten consecutive red monthly candles into early August. A split outcome, one proposal advancing while the other stalls, would say more about how validator and delegator interests actually diverge on Solana than any single governance vote has shown so far.