preferred on

Points of Focus
- In Q2 2026, Solana DEX volume dropped 45% to its lowest point since Q3 2024.
- Once the main driver, memecoin activity now makes up about 15% to 20% of spot traffic.
- RWA supply surpassed $4B by late August, and tokenized assets reached $5.8B in Q2 DEX volume (up 114% quarter over quarter).
Solana’s decentralized exchange activity fell significantly in the second quarter of 2026. Despite the network’s continued dominance in global spot DEX share, absolute volumes still decreased. The decrease corresponds with a cooling of the high-turnover memecoin trading that characterized previous cycles.
Yet, on the same chain, tokenized equities and real-world assets have set multiple records.
The question remains whether the new infrastructure can transform largely idle tokenized value into continuous trading, lending, and fee production, or if the network merely exchanges one short cycle for another.
Where the 45% drop originates
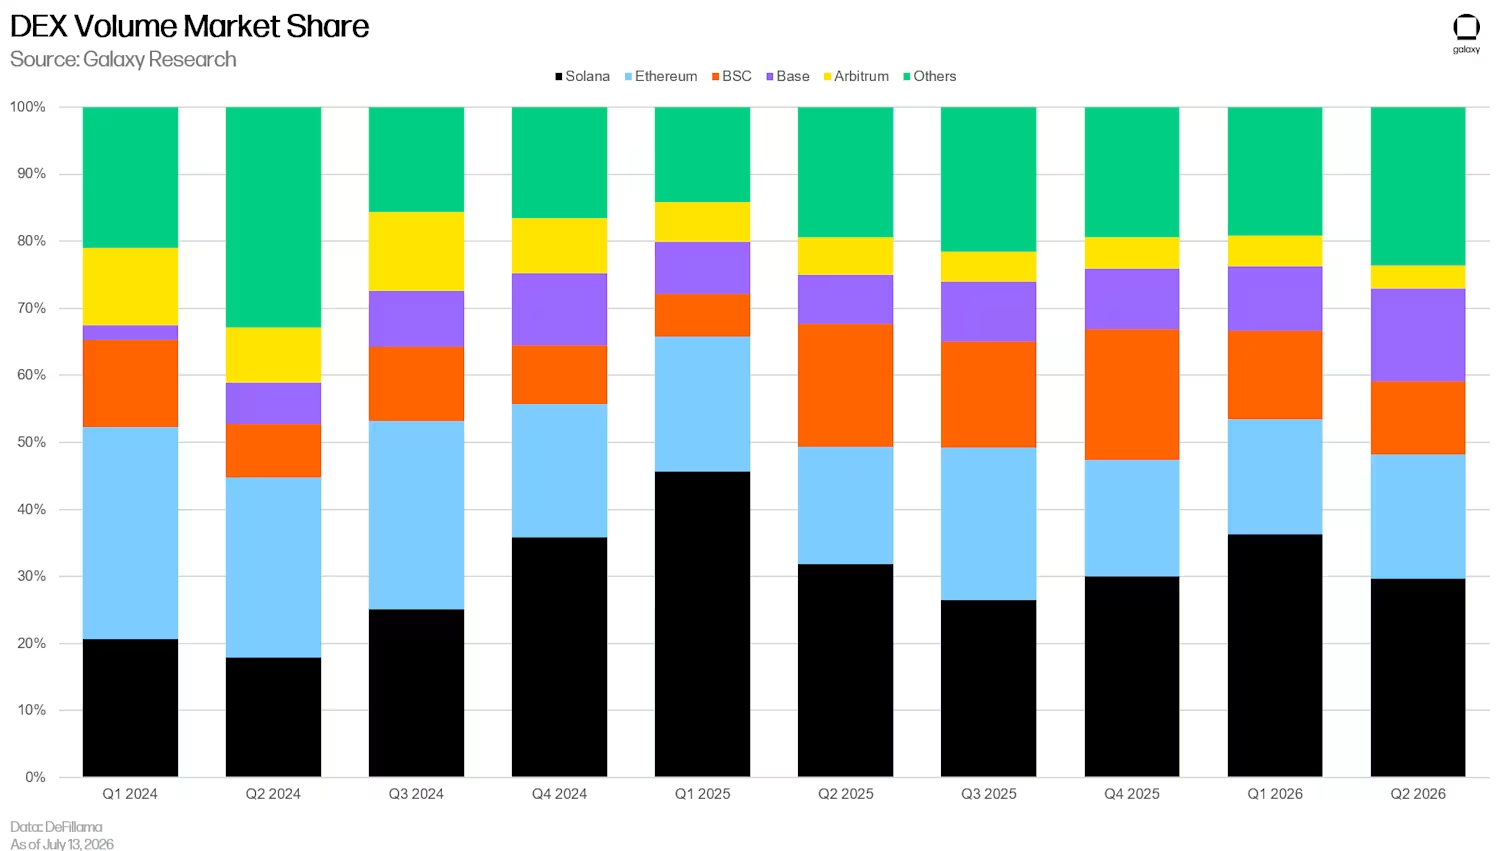
Galaxy Research’s Q2 2026 Solana report states that DEX volumes declined 45% quarter-over-quarter, reaching their lowest aggregate levels since Q3 2024. The data shows $160.8B in spot DEX volume for the quarter, a 44% decrease from Q1’s $288.5B.
Monthly numbers show the trend: volumes declined from $52.3B in April to $48.0B in May, before rising 26% to $60.5B in June. The June surge was accompanied by more listings of tokenized assets like SPCX and less memecoin activity surrounding the $ANSEM token. Solana remained first in DEX volume for the tenth consecutive quarter, but its market share fell six points to 30%, the lowest since Q3 2025.
The SOL-stablecoin and stablecoin-to-stablecoin pairs now dominate the market. According to the same Galaxy research spot DEX tracking, memecoins provide 15-20%, while tokenized stocks and wrapped foreign tokens account for around 10%.
How the memecoin phase expanded and cooled
For many years, high usage on Solana was fueled by memecoin trading and high-frequency strategies, especially in late 2024 and early 2025. Solana-based launchpads like Pump.fun industrialized token creation, producing tens of thousands of new tokens in a single day during peak periods. Bonding curve to DEX graduation rates were modest, frequently less than 2%, but the sheer volume of launches and secondary trading produced significant DEX throughput and application costs.
By Q2 of 2026, the composition had altered. Although the intensity of speculative turnover decreased, new token launches remained at high absolute numbers, and Pump.fun continues to account for the vast bulk of Solana token mints.
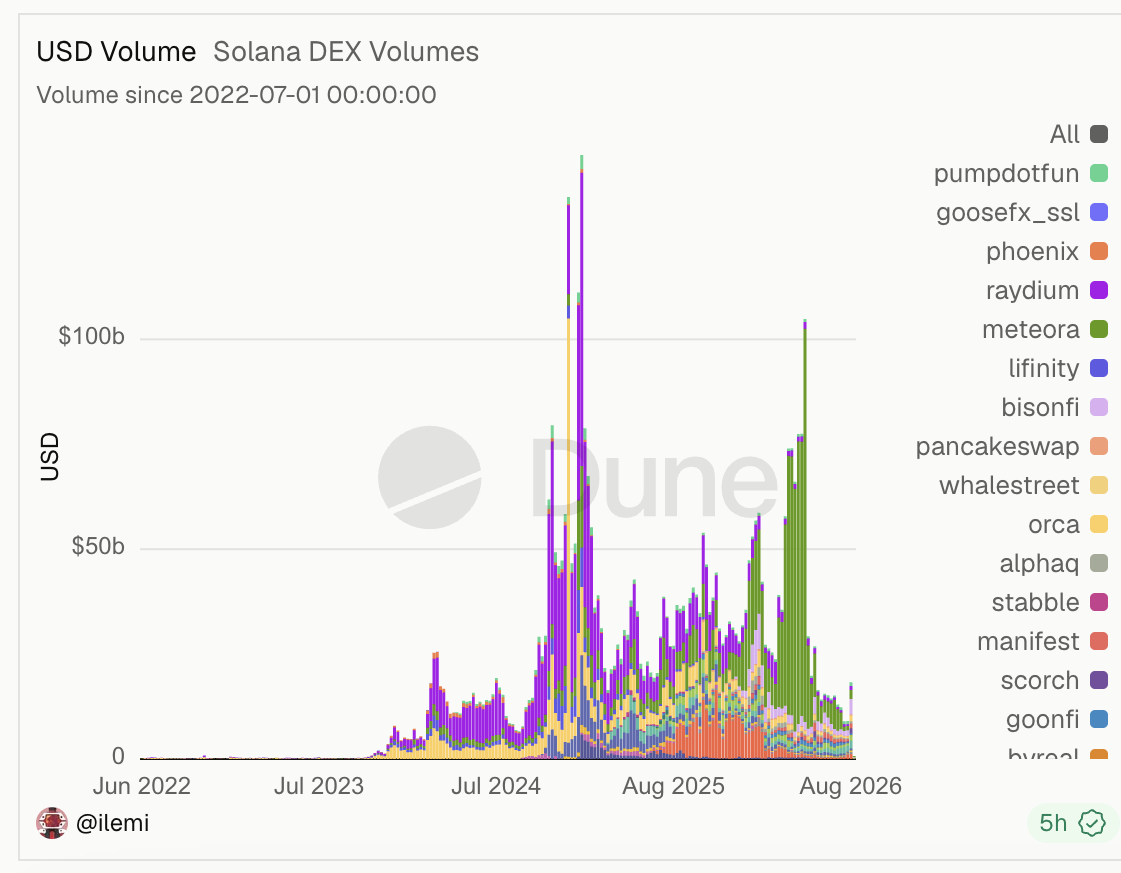
According to Dune-based reports, weekly DEX volume had already dropped by around 82% in two weeks in May 2026, from roughly $104B to $18.8B, with Meteora alone losing over $80B.
The cooling is significant for Solana since memecoin activity previously concentrated fees and caused spikes in priority fees. Application fees remained the highest among chains in Q2, totaling $552M, while Pump.fun still accounted for a sizable portion. As congestion-driven priority fees declined, network fees plummeted by 44% to around $155M. Staking yields drifted lower, with inflation still comprising nearly 90% of nominal yield.
Tokenized assets grow while overall volume decreases
In the same quarter that total DEX volume fell, Solana tokenized asset volume reached $5.8B, showing an increase of 114% from the previous quarter and marking the sixth consecutive quarterly all-time high. The vast majority, roughly $4.8B, was made up of tokenized equity, and Solana accounted for at least 95% of all on-chain tokenized equity trading during that time.
RWA supply topped $4B on August 23, 2026, after crossing $3B mark for the first time in June 2026. Public equities became the largest RWA category, surpassing private credit. Infrastructure achievements included the Securitize-Jump-Jupiter regulated equity stack in May, Backpack Securities and Sunrise broker-dealer structures under UCC Article 8 in June, and the use of Galaxy’s GLXY token as collateral on Kamino.
Solana's RWA ecosystem hit a new ATH: $4B+ in total value pic.twitter.com/mfH1wbCoBS
— Solana (@solana) August 23, 2026
This isn’t abstract prioritization. Once designed for memecoin microtrades, the same execution environment now facilitates professional order types through Jito’s JTX, atomic issuance and settlement of regulated equity products, and PropAMM liquidity. Tokenized stocks and foreign tokens make up a quantifiable and also expanding part of the remaining activity.
Where new money actually enters
Tokenized issuance generates on-chain supply, but long-term growth requires that supply to circulate. According to Galaxy Research, only about 9% of Solana’s tokenized RWA value (or approximately 16% excluding issuer reserves) is actively deployed in DeFi as trading liquidity or loan collateral.
The rest sits in wallets. Jupiter and Kamino own the vast bulk of the deployed tokenized stock collateral.
In the second quarter, stablecoin supply on Solana remained about $15.6-16.3B, with minimal growth. While velocity remains stronger than on Ethereum, the conversion of tokenized stocks and Treasuries into borrowing demand has been restricted.
Raydium handled the largest share of the tokenized equity volume. By mid-2026, the venue’s total tokenized stock volume had hit $3-4B. Secondary trading of names such as AAPLx, NVDAx, SPCX, and others shows that liquidity can emerge when distribution and legal wrappers align. The limit is not issue capacity or execution speed, but the rate at which such assets become productive collateral and generate recurrent fees comparable to the previous memecoin regime.
Tokenized assets as a growth driver
One thing is evident from the numbers: economic conversion has lagged behind capabilities. Solana now supports regulated equity, broker-dealer ownership, and DeFi connection. Even though overall DEX volume has decreased, trading volume in the tokenized category has continued to rise.
Measurable results will determine whether this becomes a long-term growth driver. The essential criteria are the percentage of RWA supply that flows from idle wallets to collateralized positions. Also, the share of total DEX volume that tokenized pairs can sustain without a memecoin comeback, and the fee contribution relative to the previous speculative base are vital.
SIMD-0550 (accelerated disinflation) and SIMD-0553 (resource-based burns) are governance measures that try to correlate network utilization to SOL value capture more closely, but their overall influence is still uncertain as of August 2026.
🚨BREAKING: @Solana’s Double Disinflation proposal is now live in the support phase.
It needs 10% of active stake, or 43.27M $SOL, to advance to a full governance vote. It currently has 16.93M $SOL in support, reaching 39.1% of the threshold. pic.twitter.com/ptD7javQgB
— SolanaFloor (@SolanaFloor) August 3, 2026
August’s daily DEX volumes and recent non-vote transaction counts have already recovered above Q2 trough levels. This suggests that the activity floor is not static. The structural challenge, however, is the conversion of the $ 4B-plus RWA base into ongoing on-chain economic activity rather than static holdings. Until that conversion rate goes well above the current single-digit proportion, tokenized assets will serve as a growing but secondary component of Solana’s volume and fee profile.
Limitations and counterpoints that continue to constrain
Several reasons keep the upside uncertain. Much of RWA development is still driven by primary distribution and secondary speculation, rather than deep, multi-protocol utility. Only roughly 9% of the tokenized value is actively used in DeFi. The remainder remains idle.
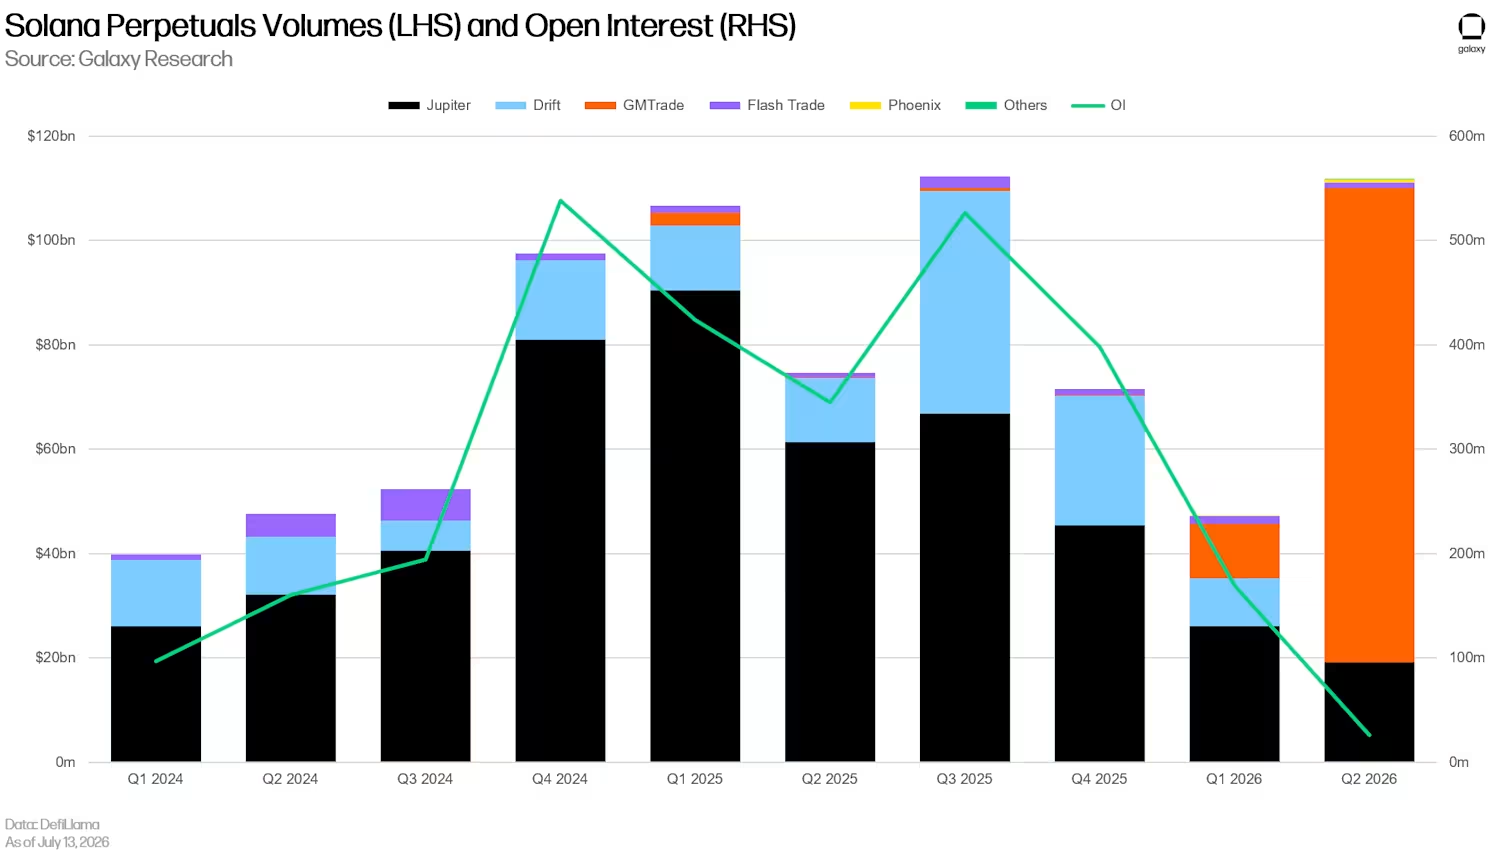
Airdrop farming contributed to the volume headlines for perpetuals in Q2. Of the $111B total, GMTrade alone contributed about $90B while open interest remained unchanged. Without that action, perps volume decreased by 43%. In the highest-value derivative markets, hyperliquid continues to maintain deeper liquidity. Prediction-market activity was concentrated off Solana.
Pump.fun continues to see a high absolute rate of memecoin launches. The compositional shift seen in Q2 could be reversed if that category experienced a strong comeback and swiftly reclaimed its share of both volume and fees. These limits do not undo infrastructural progress, but they do demonstrate why tokenized assets have not yet replaced the previous growth engine on a net basis.