preferred on

Point of Focus
- Crypto-collateralized lending contracted by $11.33 billion, or by 17%, in Q2 2026.
- Galaxy says the decline differs from 2022 because leverage is reduced gradually.
- Outstanding loans on decentralized lending apps fell by $7.79 billion, or by 28%.
Crypto’s lending market suffered another substantial contraction in the second quarter of 2026, with crypto-collateralized loans falling by $11.33 billion, or BY17%, to $56.16 billion.
At first glance, the figures evoke uncomfortable memories of 2022, when falling asset prices, excessive leverage and opaque counterparty relationships helped turn a market correction into an industry-wide credit crisis. Major lenders failed, customer withdrawals were frozen and cascading liquidations exposed how interconnected, and fragile, the sector had become.
Galaxy Research argues that the current decline is fundamentally different.
Rather than experiencing an abrupt collapse, the market appears to be deleveraging in measured stages. Crypto-backed lending has now contracted for three consecutive quarters, but the declines, 10%, 5% and 17%, have been considerably more controlled than the 55% plunge recorded in the second quarter of 2022.
The distinction matters. Falling loan balances do not necessarily indicate systemic distress. They may also reflect borrowers voluntarily reducing risk, lenders tightening standards and speculative strategies becoming less attractive. Galaxy’s data suggests that these more orderly forces, rather than widespread insolvencies or forced liquidations, are driving the current downturn.
That does not mean the market is risk-free. DeFi borrowing has fallen sharply, leverage remains concentrated in some Ethereum-based strategies and greater dependence on a small number of lenders creates its own vulnerabilities. But the underlying market structure looks more capable of absorbing the decline than it did four years ago.
$56B market after three quarters of decline
Galaxy divides crypto-collateralized lending into three broad categories: centralized finance, or CeFi; decentralized lending applications; and the crypto-backed portion of collateralized debt position stablecoins.
All three declined during the second quarter, the first time this had happened since the final quarter of 2022.
The combined market ended June at $56.16 billion, 40% below its Q3 2025 high of $78.69 billion. The headline contraction was therefore not an isolated quarterly event. It was the latest stage in a deleveraging cycle that began after the market’s 2025 peak.
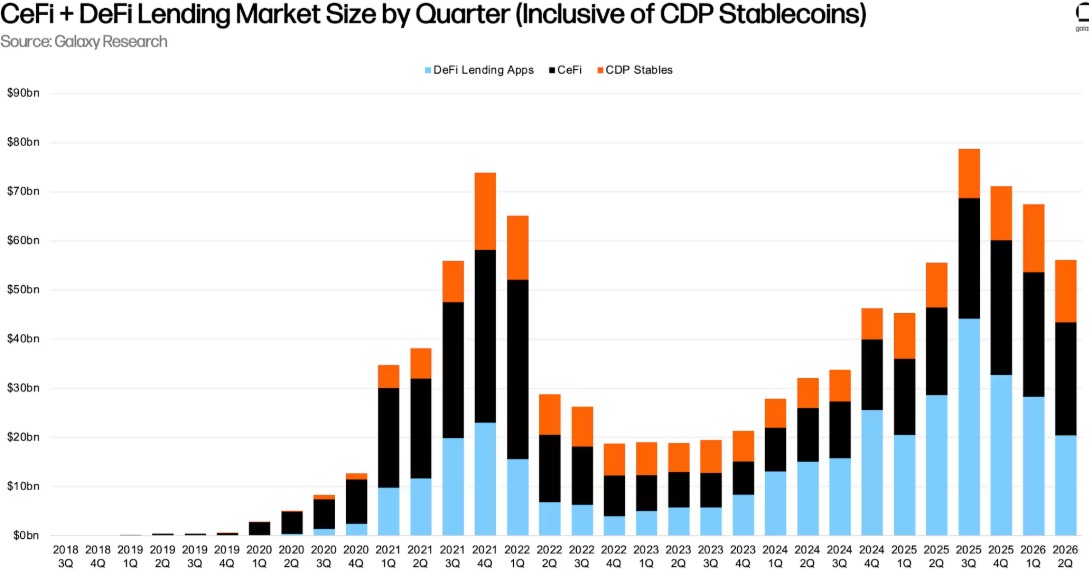
DeFi accounted for most of the quarterly decline. Outstanding loans on decentralized lending applications dropped by $7.79 billion, or 28%, to $20.43 billion. CeFi loans fell by $2.45 billion, or 9.6%, to $22.98 billion, while crypto-backed collateralized stablecoin debt declined by $1.09 billion, or 7.9%.
Together, CeFi and DeFi platforms held $43.41 billion in outstanding crypto-backed loans at quarter-end, down 19% from Q1.
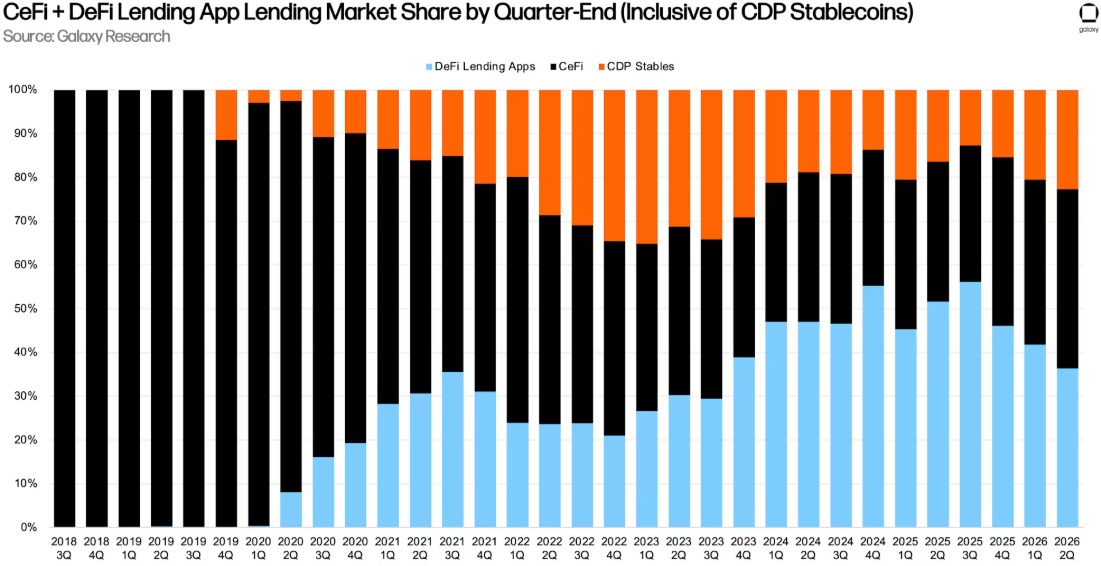
The downturn has also altered the lending market’s composition. DeFi applications represented 36% of total crypto-collateralized lending at the end of Q2, compared with 41% for CeFi and 23% for crypto-backed collateralized stablecoins.
When DeFi applications and stablecoin protocols are combined, onchain markets still controlled 59% of lending. However, their share fell by more than three percentage points during the quarter.
For the first time since Q3 2023, CeFi loan balances exceeded those on DeFi lending applications.
Why this does not look like 2022
The most important difference between today’s contraction and the 2022 crisis is not its direction but its speed and mechanism.
In Q2 2022, crypto-backed lending collapsed by more than 55% in a single quarter. It then declined by another 9% in Q3 and 29% in Q4. The initial shock was severe enough to expose lenders that had combined weak collateral practices, maturity mismatches and concentrated counterparty exposure with inadequate liquidity.
Once confidence disappeared, firms faced withdrawal demands they could not meet. Forced asset sales pushed prices lower, worsening collateral shortfalls and triggering further liquidations. Distress at one institution quickly spread to creditors, borrowers and trading partners.
The current sequence looks markedly different. Three quarterly declines of approximately 10%, 5% and 17% indicate that leverage is being removed step by step rather than through one violent cascade.
Galaxy describes the process as lending markets “taking the stairs down, not the elevator.”
That pattern supports the view that borrowers are repaying loans or closing leveraged positions progressively. Lenders may also be reducing exposure selectively without facing the kind of liquidity runs that overwhelmed centralized platforms in 2022.
There is another structural distinction: a larger portion of present-day lending activity is visible onchain. Smart contracts do not eliminate financial risk, but they make loan balances, collateral and liquidations easier to monitor. Automated collateral requirements can also reduce the scope for unsecured or poorly documented exposures to accumulate unnoticed.
Even in CeFi, the contraction was not universal. Galaxy, Coinbase, Ledn, Arch, Sygnum and Milo reportedly expanded their loan books during Q2. The aggregate decline was driven largely by a reduction in Tether’s secured loans, rather than broad-based failures among tracked lenders.
This is retrenchment, in other words, but not yet evidence of a sector-wide solvency event.
DeFi is carrying the heaviest deleveraging burden
The 28% quarterly fall in DeFi borrowing is the clearest sign of pressure.
Outstanding loans on DeFi applications reached a record $47.13 billion on Sept. 19, 2025. By July 21, 2026, they had fallen to $21.94 billion, a reduction of $25.19 billion, or 53%.
Several factors can drive such a decline. Falling collateral values reduce the dollar value of loan books even when borrowers do not close positions. Lower expected returns can make leveraged strategies unattractive, while cautious users may repay debt before their collateral approaches liquidation thresholds.
Borrowing costs also matter. Galaxy’s weighted average stablecoin borrowing rate rose by 27 basis points during Q2 and climbed to 3.9% after quarter-end. Benchmark over-the-counter rates for USDC and USDT fluctuated between 4.3% and 5%.
When the return available from a leveraged trade no longer comfortably exceeds its financing cost, borrowers have an incentive to unwind. That process can produce a significant reduction in outstanding debt without requiring mass liquidations.
The recent data offers tentative evidence that the decline may be stabilizing. Galaxy said the contraction in DeFi borrowing intensified after Q1 but had begun to ease by late July. That is not enough to establish a durable bottom, but it is inconsistent with an accelerating credit spiral.
Aave shows where the remaining risk sits
A closer look at Aave V3 Core, the largest onchain lending market in Galaxy’s analysis, illustrates both the resilience and the residual risks of the current system.
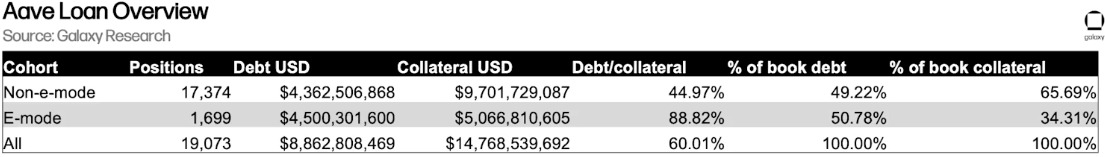
Galaxy examined 19,073 open loans in an August 7 snapshot after excluding very small positions and applying other filters. Just 8.91% were operating in Aave’s efficiency mode, or e-mode, yet these positions accounted for roughly half of outstanding debt.
E-mode allows borrowers to use highly correlated assets, such as different forms of staked or wrapped Ether, with more capital efficiency. Because the assets are expected to move together, users can borrow at higher loan-to-value ratios.
This design supports looping strategies. A user can deposit a liquid staking token, borrow ETH, stake that ETH and deposit the resulting token again as collateral. Repeating the process magnifies exposure to the difference between staking yield and borrowing costs.
It also magnifies risk.
Galaxy found that e-mode positions had a debt-weighted loan-to-value ratio of approximately 90%, an average health factor near 1.06 and debt-to-equity of about 10.7. At that level, a relatively small divergence between collateral and borrowed assets can push positions toward liquidation.
The less leveraged “vanilla” portion of Aave’s book looked considerably more conservative, with a debt-weighted loan-to-value ratio near 49%, a health factor around 1.79 and debt-to-equity of roughly 1.07.
Risk is also highly concentrated in the Ethereum ecosystem. WETH, weETH and wstETH collectively represented approximately 54.6% of enabled collateral in the filtered Aave book. Within e-mode, staking and restaking wrappers made up around two-thirds of collateral, while WETH accounted for roughly 73% of debt.
That concentration does not resemble the opaque corporate counterparty risk of 2022, but it could still become a transmission channel if an Ethereum staking derivative loses its expected price relationship with ETH.
CeFi has recovered, but concentration remains high
Centralized crypto lenders held $22.98 billion in open loans at the end of Q2. Despite falling by 9.6% during the quarter, the total remained 236% above the bear-market low of $6.8 billion recorded in Q4 2023.
CeFi lending is nevertheless still 37% below its Q1 2022 record of $36.58 billion, suggesting the industry has not returned to the scale reached before its last crisis.
The composition of that market also warrants attention. Tether controlled 59% of the CeFi lending tracked by Galaxy. Together with Maple and Nexo, the three largest lenders accounted for 75%.

Such concentration can be interpreted in two ways. Larger, better-capitalized lenders may be more capable of managing liquidity and absorbing losses. But reliance on a few institutions means that a policy change or disruption at one firm can have an outsized effect on aggregate credit availability.
CeFi data is also inherently less transparent than DeFi data. Galaxy notes that private lenders disclose their loan books inconsistently and that some third-party figures have not been formally vetted. There is also potential double counting when a centralized lender borrows through a DeFi protocol and then extends those funds to an offchain client.
The exact size of the market should therefore be treated as an informed estimate rather than a perfectly consolidated balance sheet.
Futures and corporate debt point to controlled retrenchment
Other forms of crypto leverage reinforce the orderly-deleveraging thesis.
Futures open interest, including perpetual contracts, declined by only 3.1% during Q2 to $103.2 billion. Bitcoin open interest fell by 6.2% to $45.04 billion, while Ether open interest dropped by 26% to $21.99 billion.
By the end of July, however, total open interest had recovered to approximately $114 billion. Bitcoin and Ether open interest also rebounded from their quarterly lows.
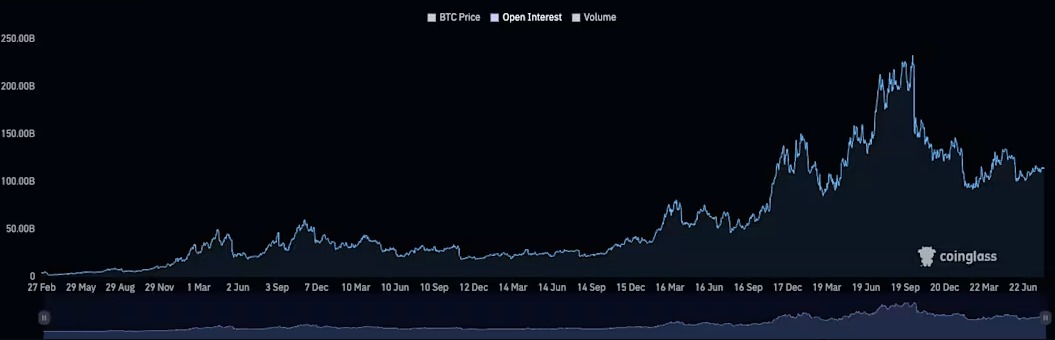
Open interest is not a pure measure of leverage because some derivatives positions are hedged against spot holdings. Even so, the post-quarter recovery suggests traders were not abandoning derivatives markets in a sustained rush.
Debt associated with digital asset treasury companies also declined. Galaxy tracked $16.1 billion in borrowing used to purchase digital assets or supplement corporate treasury strategies, down $1.5 billion after Strategy completed a debt repurchase in May.
Including corporate treasury liabilities, total crypto-related debt fell by 15% quarter over quarter to $73.2 billion. As with lending, the decline was material, but it was associated with identifiable balance-sheet reductions rather than widespread defaults.
An orderly decline is not the same as a safe market
Galaxy’s central argument is persuasive: Q2’s contraction does not currently resemble the uncontrolled credit collapse of 2022.
Loan books are shrinking gradually. Multiple CeFi lenders are still growing. Futures activity has rebounded. DeFi’s transparent collateral mechanisms are functioning, and early third-quarter data suggests borrowing may be starting to find a floor.
But an orderly decline can still expose weaknesses. Aave’s e-mode positions operate with narrow safety margins, Ethereum-linked collateral is concentrated and CeFi remains dominated by a small group of lenders whose books are difficult to verify independently.
The market has avoided a cascade partly because collateral relationships have continued to behave as expected. A sharp asset-price shock, stablecoin disruption or depegging of a major staking derivative could test that stability.
For now, however, the evidence points to risk being reduced rather than forcibly expelled. Crypto lending has lost $11.3 billion in a quarter and more than 40% of its value since the 2025 peak, but it has done so without the frozen withdrawals, institutional failures and contagious defaults that defined 2022.
That makes the current episode a significant deleveraging cycle, but not, at least yet, a credit crisis.